
根据 Bryan Cheong 的原有视频或图文整理,由 Syntax Technologies 更新于 2026 年 9 月 28 日。
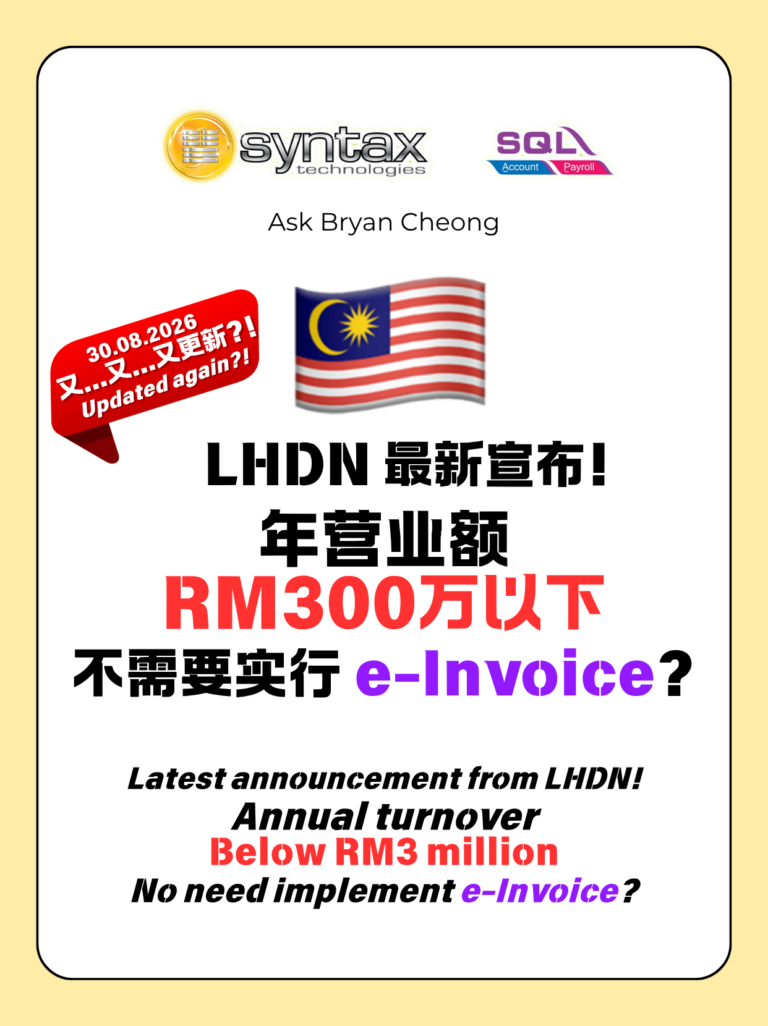
年营业额或收入低于 RM300 万,不代表所有企业都自动豁免 e-Invoice。还需要检查开业时间、相关课税年度、股东及关联主体条件。
Revenue below RM3 million does not automatically exempt every business: timing, revenue history and ownership conditions also matter.
本文根据原帖八张图文整理。图中展示 e-Invoice Guideline Version 4.8,发布日期为 2026 年 8 月 30 日,相关门槛调整从 2026 年 9 月 1 日生效。本文也链接至 2026 年 9 月 4 日更新的 LHDN General FAQ,方便核对后续说明。
中文:RM300 万门槛要怎样理解?
图片第六张摘录的条款使用“少于 RM3,000,000”。刚好 RM300 万与低于 RM300 万并不相同。企业应使用适用年度的营业额或收入资料,不能只凭某个月销售额或银行余额作判断。
2023 至 2025 年开始营业
第五张图片说明,2023 至 2025 年开始营业、年营业额或收入达到 RM300 万或以上的企业,相关实施日期为 2026 年 7 月 1 日。实际应结合企业的课税年度和适用条件核对。
2026 年起开始营业
图中说明的基本日期为 2026 年 7 月 1 日,或企业开始营业之日。不过,如果首年预计营业额或收入低于 RM300 万,实施时间为达到 RM300 万的年度之后第二年的 1 月 1 日。若符合豁免且尚未达标,应继续监测收入与资格。
小公司也可能不符合豁免
第七张图片列出三类排除条件:相关非个人股东、控股公司,或关联公司/合资企业的年营业额或收入达到 RM300 万或以上。这里的“关联公司”有法定定义,不能单看是否同一个老板。
企业现在可以做什么?
- 记录实际开业日期,并整理相关年度收入。
- 列出股东、控股、关联及合资结构。
- 把实施时间与负责人写入内部清单。
- 保留判断依据,并让税务顾问核对复杂情况。
如企业已经实施,想知道是否可以停止,请阅读 低于 RM300 万可以停止 e-Invoice 吗?,不要只根据一张门槛图片停用系统。
English: what changed and what should businesses check?
The original image set highlights the RM3 million exemption threshold and extracts from e-Invoice Guideline Version 4.8, dated 30 August 2026. The announcement image states that the increased threshold takes effect on 1 September 2026. This is a guide to those pictures, with a link to the subsequent official FAQ for context.
Businesses starting in 2023–2025
The illustrated guideline identifies 1 July 2026 for new businesses in this group with annual turnover or revenue of at least RM3 million. Check the relevant assessment periods and your circumstances before applying the date.
Businesses starting from 2026
The image describes 1 July 2026 or the commencement date as the starting rule. Where first-year turnover or revenue is expected to be below RM3 million, it describes implementation from 1 January in the second year after the year the threshold is reached. Continue monitoring both revenue and exemption eligibility.
Ownership conditions still matter
The exemption extract excludes specified cases involving a non-individual shareholder, holding company, or related company/joint venture with annual turnover or revenue of at least RM3 million. Review the actual ownership and control structure rather than assuming that every small entity qualifies.
Prepare annual figures, commencement details and an ownership chart, then record the applicable date and responsible team. If you already issue e-Invoices, see the separate guide on whether a business can stop. An exemption does not remove accounting and tax record responsibilities.
原帖图片与条款摘录 | Original pictures and guideline extracts
以下保留原帖全部八张图片,按原顺序排列。图片是当时发布的资料记录;实际执行前请核对官方更新。All eight original pictures are retained below. They record the published update and should be read with current official guidance.


常见问题 | Common questions
RM300 万门槛是否等于免报税? | Does exemption remove tax obligations?
不是。电子发票责任与其他税务、会计和记录保存责任必须分开评估。No. e-Invoice eligibility and other tax, accounting and record-keeping duties are separate.
应该以图片还是官方文件为准? | Which source should I follow?
图片帮助理解当时的更新;实际执行应核对 LHDN 官方 FAQ 和适用文件。Use the pictures to understand the update, then check the official documents for your implementation decision.
资料来源 / Sources: this post’s original eight images; LHDN General FAQ updated 4 September 2026.
需要 SQL 软件培训或技术支持?
Syntax Technologies 提供 SQL Accounting 与 SQL Payroll 销售、培训和技术支持。欢迎致电 012-663 9318 或电邮 info@syntech.com.my,说明您使用的软件版本及需要处理的问题。
For SQL Accounting or SQL Payroll sales, training and support, contact Syntax Technologies at 012-663 9318 or info@syntech.com.my.